Booming Indian SaaS Ecosystem

Indian SaaS ecosystem is at the cusp of transformation. According to Nasscom, India’s total SaaS revenue breached the $3.5 billion mark as of March 2020, growing at a CAGR of 30% and the SaaS industry has the potential to grow 6X to $13-15 billion by 2025. Indian SaaS has evolved into a multi-billion dollar industry today with startups raising growth capital from both domestic and international VCs. Homegrown B2B companies like Zoho, Freshworks, and Chargebee have become top global companies, which reinstated the confidence of investors in the Indian B2B SaaS business. Indian SaaS startups are now getting valuation multiples at par with global peers.

At Kae Capital, we are very bullish on India’s SaaS potential and have been investing in SaaS since 2012. Around 25% of our portfolio consists of SaaS startups. We were the first institutional investor in SaaS startups like Mayadata, Hippo Video, and Disprz. Our broad thesis on SaaS has remained built from India for the world and founders with unique insights about the market. (Please write to veenu@kae-capital.com or gaurav@kae-capital.com if you are building interesting SaaS businesses and want to have a discussion)

Sales Stack- The pandemic has accelerated the adoption of Remote Selling

Sales stack existed long before the pandemic and the pandemic has only accelerated this evolution. With the advent of remote work globally, we are forced to work from our homes and companies are looking for solutions to work and collaborate with their globally scattered employees. Managers are looking for solutions to onboard, train, monitor and increase the productivity of their remote teams.

The set of softwares have evolved to meet the needs of the sales team. The Sales Stack is a set of softwares that teams can use to ensure that Sales, Marketing and Growth are aligned and able to efficiently work together to maximize revenue.

Pandemic has increased the need for such softwares to manage remote teams efficiently, which has led to evolution of many startups focusing on revenue teams. According to Gartner, by 2025 80% of B2B sales interactions between suppliers and buyers will occur in digital channels and 60% of B2B sales organizations will transition from experience and intuition-based selling to data-driven selling. Sales teams across the globe embraced the new normal and learned to collaborate and sell digitally with the help of different technology solutions.

Sales Stack can be broadly categorized into four interconnected functions-
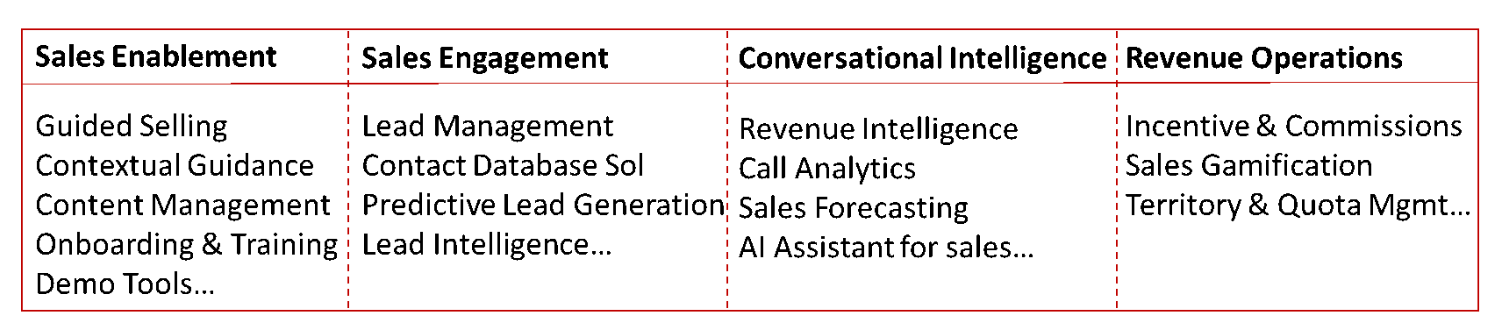
Sales stack works on top of systems of records like CRM and systems of communications/engagement like Zoom, Slack, and LinkedIn.

  1. Sales Enablement– It is the core of the sales stack, it enables the sales team with the content, guidance and training to perform their job effectively. It helps reps understand what to know, say and show to the prospects.
  2. Sales Engagement– It equips sales reps to reach and communicate with customers in a personalized and efficient way. It helps reps send the right information to the customer and keep track of actions on the leads.
  3. Conversational Intelligence– It helps managers monitor and interpret the conversations of reps and prospects. It is helpful in identifying the areas of improvement for reps. Simply put, it helps to listen and learn from sales calls.
  4. Revenue Operations– It is an end-to-end business process to provide transparency across marketing, sales, and renewals. In simple words, it streamlines the processes to align revenue teams, providing them with better visibility of the sales funnel.
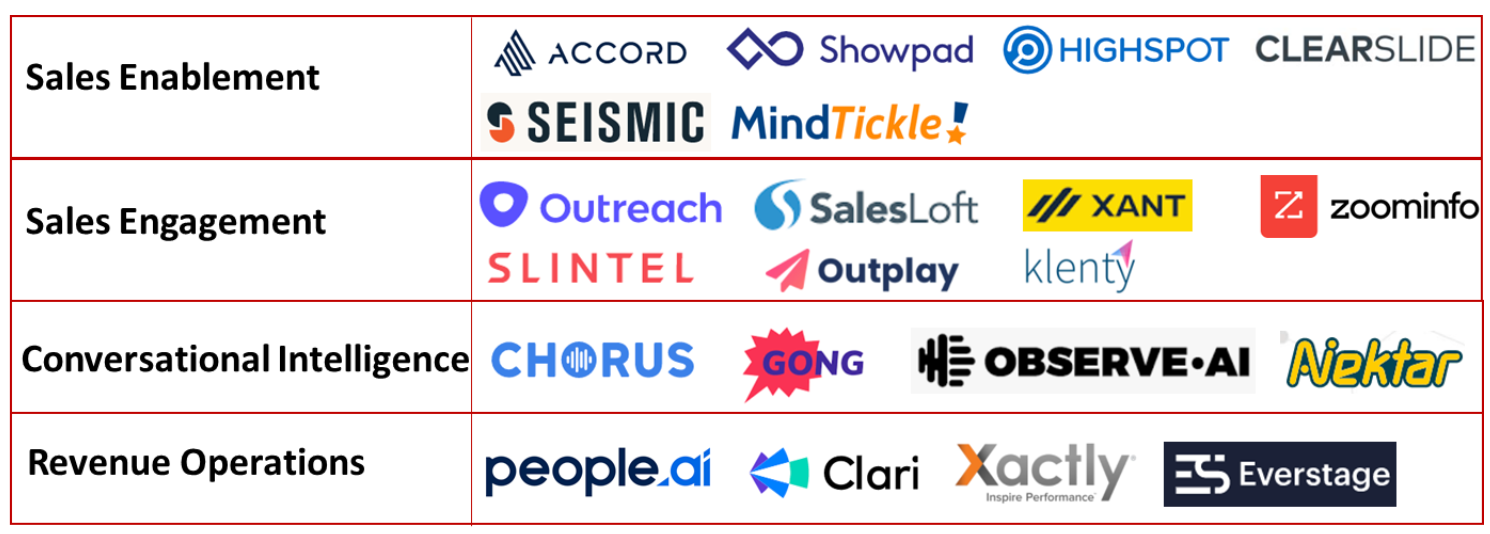
We at Kae Capital are very keen on the sales stack. We have been analyzing this space for quite some time, there are many startups that emerged in the last year. Startups are working on land and expand strategy, entering with a piece of problem in the above four core functions with an aim to eventually provide integrated offerings for the entire sales stack. We believe a product-focused team with unique insights about the target category can tap this expanding opportunity. If you are building a sales stack software or intrigued to have a discussion, do write to me at veenu@kae-capital.com

Did We Forget About Skills Along The Way?

India inherently was a nation that encouraged skill building in all domains of life but somewhere along the way, we lost track of this, becoming synonymous with a mass producer of an under-skilled technical workforce (with all due respect to the tech gurus out there, numbers don’t lie). Today we face a mass skilling gap especially when it comes to white-collar non-tech roles beyond the technical profiles, which I will briefly be touching upon.

Ancient India had its roots deep in specialization

Ancient India followed the principles of Karma, Varna, and Dharma, which assigned occupations to people based on the need to maintain a system in society. The ancient education system thrived on collaborating skills, specialization, and duty in tune with the functions of society.

The drawbacks of this system were much clear in the years that followed but for the scope of this note, we will focus on the merits alone. This system encouraged individuals to be specialized and by virtue of having a joint family system, individuals were constantly in contact with the family occupation and it was natural to be employed in the traditional family occupation.

Switching trades was not a popular option

Purely because picking the family trade brought with it a metaphorical Starter kit (tips and tricks of the trade, a.k.a skills), that were passed on from the ‘family elders’.

As the industrial revolution set in, the creation of gig work and mass culture became the first threat to this system

Money became the prime motivator of the workforce and we started levitating towards income generation above all else. Not to undermine any of the struggles of millions who lost their jobs out of necessity. Lots of individuals migrated to find a better life and opportunity. Somewhere along this journey, we lost our focus on developing skills and our pride in perfecting them over generations.

Fast forward to today

In India, 1 in 100 migrants moves out for education. 1 in 3 professionals in India is career sleepwalking and nearly 60% agree that switching careers to find a better opportunity is always on their minds.

Today, we have the third largest number of students pursuing higher education every year, succeeded by China and USA.

And yet, unfortunately, we rank 107 out of 141 countries in terms of workforce skills, and India Skills Report 2021 reported that today’s youth’s employability reduced to 45.9% from last year’s 46.2%.

Our Gross Enrollment Ratio stands at 26% which is projected to get to 50% by 2030 (optimistically)

So what does this mean for the future?

Based on this projection, it is safe to conclude that a lot of individuals (>100Mn) will be pursuing higher education in the next 10 years and a lot more will be pursuing diversified courses (not just engineering).

An interesting study also shows an early trend in dropping enrollment in professional (technical) courses in India. This would mean that a substantial part of the population that may have chosen engineering or medicine as an obvious option earlier, is now open to exploring more courses within the non-technical courses category.

Graduates from non-technical courses currently chose to apply for government jobs as a go-to option, with a few others opting for further studies. Very few elites have access to placement cells and a chance to pivot. Today this group is to the tune of ~18Mn non-tech graduates (based on our estimates).

Companies have realized the potential of this (non-tech) underdog, since a graduate from B.Arts and B.Com is reported as being as employable as a B.Tech grad in 2021. {Number crunching – this has gone up from ~26% (in 2015) to 45% (in 2021) for the former, compared to 54% (in 2015) down to 46% (In 2021)}

With a drop in enrollment in tech, a gradual skewing of the population towards non-tech and a GER target of 50% being a few of the many reasons, there is a high probability of a larger number of non-technical graduates than ever, coming out of the higher education ecosystem. For sure not all of them will go on to do government jobs or try to become technically skilled as is also supported by this survey done by LinkedIn (Jobs on the rise in 2021).

A fresh stream of professions

Then where will they be employed? Given the high amount of digitization and creation of SMBs in India, a likely consequence would be more jobs in sales, digital marketing, lead generation experts, SEO experts, design etc. There will be a large pool of non-tech jobs available which graduates will not have skills to pivot to.

We can see a rising trend for the sales and business development profiles for the last year since today on Naukri.com (which captures over 70% of the job recruitment marketplace) there are ~20,000 jobs in digital marketing and ~20,000 in sales (profiles like Sales Consultant, Sales Operations Assistant, Inbound Sales Specialist etc) for people with 0-2 year of experience. Comparing this to the number of technical jobs (with 0-2 years experience) was ~60,000, which means that for every 3 technical job openings in India for freshers, there are ~2 in sales and digital marketing with similar experience.

Given that today, we are faced with a total of 37Mn graduates (tech + non-tech) and a large chunk of them trying to upskill/reskill themselves without the umbrella of “elders” teaching them tricks of the trade nor having resources in college or at work, it is imperative for startups to come and solve for this gap.

If you are a team that is building for this category, with your focus being on the larger market of non-tech graduates, we would be happy to connect with you and brainstorm ideas!

Claim Processing Engines with Healthcare Delivery Networks

The vision to build a seamless link between healthcare delivery and insurance remains the goal

This is a topic which is of great interest in investing circles – health insurance; however, in order to paint a holistic picture, it has to be seamlessly integrated with healthcare delivery. India is notorious for heavy out-of-pocket expenses and a terribly inefficient claim settlement landscape – out of the USD 110bn+ healthcare market in India, IPD spends would amount to around 40-45% of which only USD 5-6 bn are processed in claims, indicating significant headroom for growth; and despite a large chunk of the market spends in OPD, the OPD insurance piece is completely untapped thus far. One of the major pain points to solve for in order to unlock value here is the claim settlement process – the vision is to make every settlement function and feel like a cashless claim.

Private insurance has been growing at 23-25% CAGR over the last few years – people are solving for distribution; however, the claim settlement piece remains to be solved, but this has to be done in tandem with creating a healthcare delivery network at the back

A healthcare provider network is critical to solving for cashless insurance claims while ensuring standardized healthcare delivery in the process. Patients are plagued with a very stressful journey in settling claims – managing documents, bills, and low visibility across the process. Hospitals need fast claim processing with minimum deductions and also suffer from poor visibility on the TPA process. Insurance companies need a broad healthcare delivery network to increase their premiums and lower operational costs during claim processing which is currently very manual.

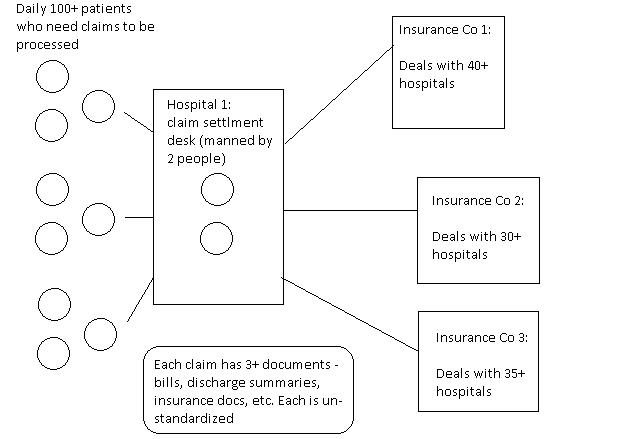
The current workflow in settling claims is severely impaired ->

The TPA desk at any hospital is manned by 1 or 2 people who in turn have to address hundreds of unique claims on a daily basis from the customers/patients and have to coordinate this with 30+ TPAs on the other end with each having their own guidelines. Similarly, Insurance cos and TPAs need to reconcile the billing information, discharge summaries, and insurance documents of different hospitals and process the claims manually – neither the hospitals nor patients have any visibility on which stage the claim is at.

There is an urgent need to solve for an automated claim processing engine with seamless information flow between the different stakeholders on a singular platform -> the patient, the hospital and the insurance company so that TATs in claim settlement can be reduced, deductions can be reduced and a patient can have a seamless experience from hospital selection to discharge, the hospitals can settle claims in a speedy fashion and insurance companies get a strong healthcare delivery network to maximize premiums.

Using technology to integrate hospitals and insurance cos on one platform is very difficult and business model positioning is complex

Since it is clear all three stakeholders need to be integrated on one platform for seamless communication and processing, there arise some critical questions which need to be addressed -> Will the start-up be positioned as a claim processing engine with a network of healthcare delivery providers in the backend and if that is the case, who will the core customer be?

By positioning as a claim processing engine with a network of hospitals at the backend, does the business model build a large enough outcome? The odds are that start-ups will charge a take rate for every claim processed. From our research, this seems to draw anywhere between 2-4% take rates which may limit the size of the opportunity, however, there seems to be a case for generating strong leads for hospitals which convert to procedures/tests for the hospital where an 8%+ take rate might work.

We are looking for companies who have unique insight into cracking the technology integration piece across all the stakeholders

Platformization of the communication and processing of claims seems to be plagued with very high adoption friction across stakeholders. The following become possible channels to drive adoption:

· The insurance companies (and TPAs) themselves –There are a limited number of health insurance providers with even fewer having a high willingness to adopt technology – seems like a tough sell on the legacy players; new age players with a tech DNA might be a low-hanging fruit.

· Hospitals – Will be a tough sell whichever way we look at it, it is common knowledge that changing/upgrading HMS systems in hospitals itself is an uphill task – making it a difficult proposition for new-age tech adoption.

Thinking out of the box to crack technology integration

· HMS systems – Since all data integrations with hospitals need to start from the hospital HMS, another viable option may be to tap into HMS cos – a single HMS provider might have access to 5k-7k hospital beds across different hospitals.

· WhatsApp – With initial indications of health start-ups having demonstrated Whatsapp-first approaches to onboarding and activating doctors, there may be a case for interesting claim processing engines being built atop of Whatsapp in a way which seamlessly connects across all stakeholders

With so many questions and such few answers, we feel putting out our thoughts will help us get some closure on the open questions surrounding a unified healthcare and insurance play.

We are on the lookout for a solution which can be adopted with minimum friction and has a scalable monetization model – if you feel you have cracked/or have insight into a stronger business model, we would love to hear it!

Women’s Health – A Massive Whitespace To Solve For

We at Kae are bullish about women’s health and feel large companies can be built out of India.

Women’s health is a pressing need in the Indian healthcare market

It is no secret that the Indian healthcare infrastructure is broken – issues include poor doctor-to-patient ratios, low healthcare/GDP spending, and poor geographic and cost accessibility across the board. These problems further complicate matters for the very critical, yet underserved women of the Indian population.

There is a pressing need for women-centric solutions across multiple verticals like nutrition, sexual and reproductive health, dermatology, and mental health, with existing legacy alternatives being subpar on multiple fronts – stigma, lack of personalized care and outcome-driven thinking have created a gaping trust void.

Why now? – Women’s health stands out as an opportunity to build loyalty through online communities

Over the last few years, women have increasingly come to rely on online channels for most of their health needs as is indicated by the sharp rise in in-bound queries (>100% YoY increase) on both Practo and Google.

All the urban women we spoke to rely on a set of digital communities for their personal health needs – and there has been an increase in the number of such groups in recent times – the plethora of new WhatsApp and Instagram groups are testament to the inherent virality that women’s communities have.


The TAM is large enough to capture the value and build out a venture-scalable business

As VC investors we are on the constant lookout for large monetizable spaces – so it is critical to target those TGs which have a consistent spending capacity with the right hook.

Much like other Indian consumer markets – the majority of the paying capacity lies in Metros and Tier-1 cities. Basis our own research by speaking to potential customers and founders alike – there exists a very high willingness to pay – with the minimum ticket size going upwards of INR 1k per month on average. Our confidence lies in the precedence of women paying periodically for both products – like pads and consumables as well as much higher ticket size procedures and services like laser hair removal, which generates a semi-annual spend of around INR 50k+ easily. Many of the recurring spending categories are must-haves for women.

Most tech solutions today are community and content led, with a paid conversion to a full stack primary care and telemedicine/teleconsult layer with products/tests or procedures on the back to monetize – we believe a sustainable business model in currently available tech platforms will be built on the back of an e-commerce platform to maximise for spend per acquired customer.

We believe the market is ripe to crack the right core customer and hit product and channel fit

The personas in this market are large enough to build out a scalable business – be it a working professional, a homemaker or student to hit PMF. High NPS and customer delight are all about solving for the best value proposition/solution for your niche and this is a question which is very much open to debate with no wrong or right answers.

The niche here we believe will depend on the stage of life the customer is in, and we believe the best way is to look at it as follows –

• 25-35 – issues may range from PCOS, irregular periods, skin and hair, etc.

• 35-45 – issues may be pregnancy-focused, fertility-related, etc.

• >45 – issues may be around menopause, skin, etc.

For each phase of life, the core hooks may vary – from dermatology to reproductive health and fertility; this a question we would love for entrepreneurs to answer!

We are looking for a team that can crack the “trust” factor

Our belief is that unfair advantages will be built around trust and brand recall– most solutions in the market today are still fairly early in their journeys and are on the lookout for weak signals of a potential hockey-stick growth going forward built on deep engagement. We are actively on the lookout for teams with the best insight into building high-engagement communities.

If you have unique customer insight and demonstrated engagement/early indicators of engagement and are confident or even have the slightest inkling that you have cracked or are on route to cracking a scaleable trust-building playbook while offering personalised and empathetic solutions in a standardized manner – we would absolutely, positively love to hear from you – please do write to sarthak@kae-capital.com.

Kae Konnect: Future of Gaming

As part of our Kae Konnect Webinar Series, we hosted Nitish Mittersain, Founder & MD of Nazara, which today is one of the leading gaming companies in India with operations across 60 countries. During the one-hour fireside chat, we deep-dived into the future of gaming and how it will shape up in the next 10 years. Nitish also discussed potential opportunities that are waiting to be unlocked along with some of his key learnings during his journey with Nazara.

If you’d like to see the video for the event, please use the link: https://youtu.be/skIYCF2jbi0

Following were some of the key highlights from the discussion:

Future of Nazara and Covid-19 Impact:

While some of the verticals were impacted negatively due to Covid-19 (eg. fantasy sports etc.), edutainment has done very well for Nazara. Kiddopia (an app focused on kids’ education and entertainment) grew its revenue by 5x during this period. Companies such as Sportskeeda pivoted to double down on e-sports and become the go-to destination for esports content with ~20 Mn users a month.

In the immediate future, Nazara plans to focus on three spaces – e-sports, early learning, and sports simulation – via its companies Nodwin Gaming, Kiddopia and NextWave (owns IPs such as WCC).

Trends in Gaming:

Nitish believes that the intersection of VR and gaming is very interesting – this space is nascent right now but he believes that we will move from 20-minute sessions to a world where it will be very difficult to get out of a VR session. Another key trend is that games will evolve into social platforms. We are already seeing certain trends such as songs being released and concerts being hosted within Fortnite. Gaming will move beyond just the gaming experience per se and deliver more value in terms of engagement and social experiences. A third big trend, Nitish predicts is the gamification of activities in our day-to-day lives. Companies such as Zwift allow users to cycle at home, compete with friends and enjoy a community of enthusiasts – therefore making the entire experience more gamified and engaging.

E-sports in India:

Mobile has been a great leveller for esports. Earlier e-sports was focused on PC and Indian gamers lacked exposure to certain gaming platforms. However today because of games such as PubG, gamers have more avenues to play competitive games and are now able to compete on a global scale. Therefore mobile is an accelerator for esports and strong growth is expected from India and other continents such as Africa. In the last year or so, we’ve seen 100s of live streamers acquire 1Mn subscribers on Youtube – another sign of the growing e-sports ecosystem.

Real Money Gaming in India:

Two success stories have played out in this space i.e. fantasy sports and rummy. Nitish believes there is still more headroom for growth. Companies with differentiated core products can continue to build in this market however founders need to be mindful of regulatory risk in this space.

Monetization of Indian Gamer:

The majority of gaming revenue in India is via real money gaming today (fantasy, card games such as poker rummy, etc.) while the balance revenue is from in-app purchases and advertisements. However, Nitish is seeing green shoots in the second category where Indian users are willing to pay for games. Nitish believes a growth of 10-20x can be expected over the next 2-3 years in in-app purchases.

Being mobile gamers first, most users in India are casual gamers. However, as these users move through their gamer lifecycle, they will eventually move from hyper-casual to casual to mid-core gaming. Indians today have access to some of the best gaming content across the globe, therefore as an Indian gaming studio, you need to build games that are at par with global competitors to pique an Indian user’s interest. Localized content and IP may help grab initial eyeballs however developers need to build strong game mechanics to ensure engagement, retention and monetization. We are starting to see successes such as Ludo King which has strong retention and virality – taking the game to over 50 Mn daily active users.

Metrics in Gaming:

Founders should avoid vanity metrics such as downloads (as users may install the game but delete the game eventually). Companies should focus on metrics such as retention and time spent, as that will determine ARPU from the user. The other key metric founders should focus on is virality. In markets such as India, the propensity for a user to pay is lower, whereas in markets such as the US, users have a higher propensity to pay (therefore the LTV/CAC ratio would be better). To help distribution, game studios should bake virality into their products when building games for India.

Advice to Founders: 

“Float like a butterfly, sting like a bee” – Nitish quotes Muhammad Ali and advises founder to be light-weighted, stay asset-light, debt-free and build strong and clean corporate governance. Nitish has four independent directors and believes that they bring different perspectives and insights to the table and show founders their true picture. Bringing in an independent director early on in a company can add tremendous value to the team.

At Kae, we resonate with Nitish’s excitement in the gaming space and believe multiple massive opportunities are waiting to be unlocked.

If you are building something in gaming, we would love to hear from you. You can drop an email at sarthak@kae-capital.com to discuss your venture.

Changing Nature of B2B Transactions: The Rise of B2B Marketplaces

The history of e-commerce is intertwined with the history and boom of online marketplaces. Using technology to connect buyers with sellers and efficiently facilitate transactions, these online marketplaces have overcome the limitations of an offline market. In an offline world, transactions are limited by geographical reach/information asymmetry and are facilitated by intermediaries, online marketplaces however opens a broader market for the buyers and sellers to meet and transact. Marketplaces also have been a go-to model for tech entrepreneurs and investors because if executed well, they have inherent structural advantages to create a large scale and unlock huge values. Some of the most successful innovative businesses of the last few decades have been online marketplaces.

Consumer marketplaces (B2C) have been around for quite some time and have gone through multiple evolutions of business models, starting from listing-focused classifieds, they evolved into transactional ‘open’ and ‘managed’ marketplaces. While we have large horizontal marketplaces like amazon where you can find anything, we also have vertical marketplaces for a specific categories like fashion, furniture, makeup, etc. Now as a consumer, we have an efficient way of buying almost everything online.

While B2C marketplaces have evolved, innovated, and have become ubiquitous in a consumer’s life, the same can’t be said about B2B. In most economies, B2B transactions usually gross up much more than B2C as every supply chain has multiple businesses in between a producer and a consumer. Unlike B2C where the transactions are usually for personal consumptions, here the purchase is typically part of a chain and the cost of delay or quality failure can be very high. Most industries have complex supply chains, low transparencies, and rely on inefficient intermediaries for trust. B2B transactions happen in different value chains/supply lanes wherein the dynamics and participants don’t usually overlap. Inefficiencies in the value chains make sure that there is a very strong case for efficient B2B marketplaces.

The Indian Landscape

India presents an even more interesting landscape. We are an economy of small businesses. 99% of Indian businesses are what is classified as a ‘micro’ business. These firms are usually ‘family’ or ‘single person’ owned, have very few employees, and turnovers in the range of a few crores of rupees per annum. Most of these micro-businesses have poor margins/efficiencies and also have low levels of technology adoption. While these small businesses are millions in number, they contribute to about 30% of the Indian GDP resulting in smaller throughput. Being largely a fragmented market dotted with millions of suppliers and buyers transacting largely in localized markets, India represents a strong case for B2B marketplaces to disrupt the traditional procurement models. Recent changes like GST, digital penetration, and a generational shift can prove to be tailwinds for this.

All market(place)s are not equal

B2B marketplaces have not always worked out. For every successful one, there are numerous more that have faltered in the long run. There can be a lot of reasons for failure like a bad economic model, poor execution, lack of investment and most importantly choosing the wrong market. There are some markets where an online marketplace (or intermediary) creates value while somewhere it does not.

Before jumping in and start building a digital B2B business, it is better to look through some factors that affect the success of one. There are numerous resources to read about it but Bill Gurley’s 2012 article “All markets are not created equal” is still probably the best starting point. There are quite a few things to think through before building a marketplace, we have listed down some of the important ones for a B2B marketplace

  1. Use of technology- First and foremost it is important to understand, what is the value technology can bring to this supply chain: Is it discovery? (increasing the number of buyers and sellers), is it user experience? (better workflows) or efficiency? (intelligent matchmaking). Also, marketplaces tend to be side oriented i.e. will solve the key problem(s) on either one of supply or demand, think through where is the bigger pain point to be solved using technology.

  2. Fragmentation- This is one of the most important factors to consider before jumping in with a marketplace. The biggest problem that a marketplace solves is discovery and transaction facilitation (by inducing trust), this is what creates value for the intermediary. In the case of supply and demand concentration, this value tends to diminish very quickly. All other things remaining equal, High fragmentation in buyers and suppliers is positive for the marketplace. High concentration on both sides, practically renders a marketplace (or intermediary) redundant. If you have to look at a market with a concentration on one side, it is usually better to build in markets where supply is fragmented.

  3. Throughput- It is important to look at what is going to be the Average order value in the supply chain and also what is the frequency of transactions. A high AOV enables the marketplace to grow faster. A high-frequency marketplace tends to be stickier with high recall value and so (generally) higher cost of shifting. Ultimately, the average transaction value, frequency, and margins (take rate) define the long-term economic viability of the marketplace. It’s important to remember that in B2B, more often than not, margins are lower than in B2C, on a per-transaction basis the unit economics (most of the time) makes sense if the average transaction value is high.

  4. Value chain margins- A key difference between consumer and B2B markets is that the inherent motivation for a business to transact is economic rather than consumption, this makes the value extraction by the marketplace to be mostly dependent on (and capped to) the overall value chain margins. Given that one of the key lures for the participants (supply and demand) is going to be an economic advantage, the take rate will be a smaller piece of the value chain margin. Interestingly, there are cases where the value chain margin is not rigid but expandable, in cases where capacity utilization/inventory liquidation/ ‘sweating the asset’ is important, dynamic pricing can unlock better margins.

  5. Commodity v/s specialized product- An online marketplace usually brings in value of discovery and trust between the transacting parties. In the case of a commoditized or branded product, trust is not that big an issue, in such cases, generally, margins tend to be much lower than specialized/custom products/services.

  6. Direct v/s Indirect- Whether the underlying product/service is direct (eg-raw material) or indirect (eg stationary) expense, defines the underlying motivation for the customer. For a direct spend, price becomes a top priority along with the expectation of zero failure rate in fulfilment. Inertia to change vendors is high in this case which results in lower take rates and longer sales cycles. If successfully executed, direct spending provides a recurring, predictable, and sticky business to a marketplace. For indirect spends, take rates can be higher but the barrier to replacement for the marketplace is comparatively lower.

  7. Monetization and business model- Depending on the value chain margins and overall marketplace dynamics, the business models can go from an open marketplace to a managed marketplace. Similarly, the monetization at scale can be through transaction take rate, subscriptions/advertising, or ancillary services (logistics, credit).

  8. Network effects/Moats- Typically open marketplaces have strong network effects and moats. For managed marketplaces specific workflows, data, and allied services can help create effective structural moats.


To summarize, it’s critical to choose the right market and business model before diving in to build a B2B marketplace. The marketplace for a custom/specialized product in a highly fragmented market has a better chance of success compared to a marketplace in a highly concentrated market with a standard product. Also in B2B specifically, it’s critical to think through how you can acquire, onboard, and manage the customers and suppliers efficiently. Because of higher-order values and the criticality of transactions, the zero human touch model is difficult to succeed (at least in the initial days). Business workflows, decision-making, and payment terms are also not simple and straightforward, one of the big challenges that the B2B marketplaces have to navigate (which their consumer siblings don’t) is managing collections, working capital, and credit. It is critical to keep it on a tight leash and put-in processes to skip the downward spiral of the cash trap.

We at Kae Capital continue to be very bullish on B2B commerce and are early investors in Zetwerk, 1K, and a vertical B2B e-commerce marketplace (to be announced soon). If you are building something in B2B, give us a shout at gaurav@kae-capital.com

Event Takeaway: Marketing Growth Hacks

As part of the Kae Webinar Series, Kae Capital organized a webinar with Praveen Rajaretnam on the topic “Marketing Growth Hacks (B2B & B2C)”. Praveen was the Co-founder & CMO at Wooplr and then Head of Product Marketing at InMobi. He currently works as Sr. Manager, Product Marketing at Freshdesk.

Praveen shared his playbook with our portfolio which you can find here

Following are some of the key takeaways from the webinar:

1. The motto of every advertiser – To understand and be understood.

An ad should reflect the fact that you understand your audience and also it should clearly convey your message. This can be achieved by keeping four things in mind – having a simple layout, a short and concise copy, legible text and a clear CTA (Call to action).

2. Data Speaks!

While coming up with ideas for ads it is important to keep your perception of the brand separate from that of the audience. Also, following current marketing and advertising trends specific to your sector without understanding what your audience really wants would do no good for your brand. Relevance is key.

3. Sell less – This is how your brand will stand out

Sell less and keep the content engaging. Quality and differentiation are the two key factors for coming up with the best ad. By being original, you help build your brand identity. Be open to experimenting with the features of various platforms and with the kind of content you put out. A fine example would be Wooplr using the carousel feature of Facebook to put content in ads.

4. Understanding the platform and audience can do wonders for your ad

Study the platform and understand its features and the kind of audience using the platform before publishing your ad. Leverage the constraints of the platform to your advantage.

5. Humour helps!

This is a no-brainer- everyone knows that the funnier the post, the more chances of it making an impact and delighting the target audience! Humour gives the brand a more humane touch and a personality, thereby helping to build brand loyalty.

6. Work on making better creatives

Multivariate testing will help you figure out your core audience in depth. Use the learnings to make better ads specific to your Brand/Product/Service. Keep on experimenting with the colour, font, copy, elements, template, etc. via A/B Testing. Collect and study the data to zero down on what works best for your brand.

To summarise- Data speaks, all you’ve got to do is listen carefully and be consistent.

You can find Praveen’s Presentation on Slideshare. Click here

How Founders Should Think About Scale Before Pitching to a VC

So you have started up recently, have just launched the product six months back, have a few paying customers, good margins, and a clear plan for the next eighteen months! You recently got introduced to this venture capitalist through a common friend and are excited to meet and pitch for a seed round.

For the last couple of years as a venture capital investor, I have had a chance to interact with hundreds of entrepreneurs. Most of them were with solid ideas, great teams and a passion to build something out. 

One of the most difficult things that I have had to do is to say ‘no’ to a lot of ideas with great founding teams which had a solid underlying business, revenue and even path (sometimes imminent) to profit. Still, that business is not a great fit with the venture capital model. 

There has always been a lack of clarity in the mind of a lot of entrepreneurs about what exactly is a ‘venture fundable’ business and why venture capitalists say no to profitable ideas while pouring millions of dollars into (seemingly) loss-making, cash-guzzling businesses!

Most of the founders do not fully understand how the venture capital business model works, (although the share of founders, who understand it is much higher than what it was 5-10 years ago). I always recommend founders first understand the venture capital business before engaging with one. A lot of good reads are already available on this topic. What I really want to convey is a simple actionable framework that can help entrepreneurs to think through before approaching venture capitalists, especially from the perspective of scale.

A <TLDR> from all the stuff that you will find about the venture capital model is that the returns follow power laws and hence first and foremost, scale matters. You will see venture capitalists can (and almost always will), take bets on seemingly difficult businesses (with a higher chance of failure) but the ones which can grow very large. Simply put, high risk but high-reward models. 

Ten minutes into a pitching session, the first question is ‘Can this become large? How large should you be thinking?’
That’s the real (100) million-dollar question.

A rule of thumb that we follow is to try and answer ‘can this business reach a $100 million, high-quality annualised revenue, in the next 7-8 years’. If the answer is yes, you have got (our) attention!

Now let us dissect each aspect of this question and flesh this whole out a little, shall we?

  1. Revenue: It’s important to emphasise here on ‘revenue’. This is not GMV, not GTV, not LTV. In case you are into an intermediary business, (for example, a marketplace), then you should think of this as the commission/take rate or gross margins. This is essentially the price, customers are paying for the value that ‘your business’ is providing.

  2. High quality: This is super important! A good quality revenue is high gross margins (usually software margins of 70 to 90%), strong predictability/repeatability (nothing like a long-term subscription revenue model), and good cashflows (generate positive cashflows with growth and you are golden). This is why SaaS (software-as-a-service) businesses are highly valued — that is as high quality as you can get.

  3. 7-8 years: Are you going to grow fast? Are the conditions (both business as well as market) conducive now for you to quickly scale? Most of the fast-growing businesses can do that because they ride some ‘wave’. New technologies usually change customer behaviours and enable businesses to grow fast.


An important point to also think through is if capital is really going to help your business grow fast. As an example, most B2B businesses traditionally could not grow very fast because of structural reasons and so even though they were in a large market, they were not as attractive to investors. The SaaS wave has changed all of that, as now companies selling to even SMBs can scale very fast.

Having understood the question, before you answer a yes or a no, take some time to also nuance some finer points and visualise how your business and the market look at scale.

First, it is critical to see if you are attacking a market where the ‘target addressable market — TAM’ is large enough to support such a business. When looking at the TAM, most of the founders go with public data and a top-down approach. The usual gist is — billions of dollars in market size and only a 0.1% market capture yields 100s of millions in revenue. This almost always doesn’t work — you wouldn’t be able to find many valuable companies with a 0.1% market share in a large market, it’s usually a larger percentage of a much smaller but highly targeted market.

While calculating ‘TAM’, I always encourage founders to do a ‘bottoms up’ market sizing to go with a top-down approach. It usually will start with you being able to define your core customer segment. The total universe of your core target customer and the price per customer will give a good estimate of the market size, at scale assume that there would be two-three large competitors eying for most of the market share and make reasonable assumptions.

It’s important to also remember that the best companies always end up increasing the TAM! Especially if you are riding a wave, it is difficult to estimate the market size ten years in the future. Still, when you are looking to bet the best part of your productive career, it is prudent to start with a large enough TAM rather than depending only on expanding market size.

There are a lot of other things that go in while evaluating a business for an investment – team, competition, business model, technology and so on, but the deeper dive is contingent on crossing the line on ‘team’ and ‘TAM’.

Now, what if after this consideration, the answer to this question is a ‘no’? In that case, you go with the good old way of building businesses — profits and cashflows. Although this way is less glamorised, this is how most of the large businesses in India (and globally) have been built. They have been financed by conventional debt and public and private equity financing. Family offices and HNIs (with patient capital) are good partners for such a business in the early days, a lot more options open up with a scale.

If the answer to the 100 million dollar question is a ‘yes’ for you, go ahead — a lot of VCs including us at Kae Capital are waiting with (our) chequebooks!

Who Is Your Customer?

Founders are often tempted to capture as much value (or revenue) as possible from different types of customers. To do this, they often wastefully spend their energies and company resources on capturing multiple types/avatars of customers and therefore lose sight of the company’s core value proposition and focus.

At Kae Capital, I’ve seen maximum value and growth generated when founders have a laser-sharp focus on one customer avatar. These founders then go ahead to build every aspect of the company around that one customer avatar (be it marketing, branding, value proposition, any hooks of engagement etc.)

This is my take on what you could do:

Defining core customer avatar: Go deep in defining the customer avatar – age, gender, ethnicity, behavioural traits and habits etc. The idea is to build all aspects of the company around the avatar and what appeals best to that customer

Firing your customer: Anyone who does not fit the above profile is not an area of focus. Fire the customer!

To help you build further on this, at Kae we came up with a framework. I think it’s a great exercise to work as a team and come up with answers to these 8 key questions.

Defining core customer avatar:

Q1. Hypothesis – Who is your core target customer? 

Be as detailed as possible in defining your core target customer. In certain B2C cases, this would be a “user” which is different from the “customer” e.g. social networks / audio platforms where the users are part of the network/consumers of content

Q2. What is your company’s core value proposition for your customers?

It’s also important to define the core value proposition of your company. What makes your offering so compelling for the customers? Why would you win against the competition? Is the core value proposition really valuable for the core target customer?

A good way to summarise the core value proposition for the core target customer is coming up with a one-line ‘positioning statement’

Q3. Validating the hypothesis – Is your core target customer deriving maximum value out of the offering?

Once you have defined the core target customer and the core value proposition, it’s critical to validate that thesis. Go deep into the customer mix and the value derivation by the customers, and look for evidence of who and in what way is deriving the maximum value out of your offering. There are a few tools that you can use to measure the value derivation and to find/ identify core customers

  • Usage/Engagement trends – Look through the usage/engagement data and notice the trends. Looking at the power user curve is a good tool for this.
  • Customer Retention/Renewal/Churn data and trends
  • NPS – Segmental NPS data can give a lot of ideas about core customer
  • Sales process and conversion data

If you do find a mismatch in the answers to Q1 and Q3, it is time to go back to the drawing board and iterate till you reach a broad match in Q1 and Q3.  

Q4. Aligning efforts – What percentage (number and revenue) does the above core customer occupy of your entire customer base?

This will help you understand how focused your energies truly are today.

Q5. Once you’ve identified your customer, what has your company done to build around this core customer?

List down 3-4 initiatives your company has taken up (in the last 6-9 months) to build a value proposition that resonates with the customer 

Q6. Going forward, how do you plan to further strengthen your value proposition for the identified customer?

As a team come up with 3-4 levers you plan to implement in the next 6-9 months which would strengthen your value proposition

Focus, focus, focus!

Fire customers who do not fit the core avatar!

Firing your customer:

Q7. Who have you fired in the last 6 months?

One of our health-tech portfolio companies fired customers who were above the age of 65 as it was a herculean task to onboard them and their ability to pay for services was low. Which avatars have you fired in the last 6 months and do you have any key learnings through this exercise?

Q8. What efforts are being taken to fire the remaining customers?

What steps are you undertaking to fire the remaining customer avatars (avatars that are not core to the business) in the next 6 months

__________________

We ask our portfolio founders to document these answers and share them company-wide – this helps every team member to align and work towards the goal.

If you are working on a consumer internet idea – I would love to discuss and brainstorm over a cup of coffee. Hope this helps!

Also, thanking Gaurav Chaturvedi and Vidushi Kamani who helped in creating this framework.

What I Learnt With Fynd

The genesis of Fynd – Harsh tells the full story here….but here’s an extract to get you started.

Since Sept 27, 2012 (when addSale was officially registered in Mumbai), we have gone through two industries, two serious potential buyers, three ground-up built teams, three names, five offices, 10 internal and external products, trying to sell in 15 countries, 22 names on the cap table, deployments across 25 cities in 100+ stores and 120+ team members.

Along all of this, we have always remained true to our passion to build products that help people shop.

Our vision was to be at the intersection of technology and retail. We wanted to straddle the gap between the ease, convenience and personalization of digital technology with the instant gratification, touch and feel experience of physical retail.


So how did we become one of the 22 names on the cap table?

I will never forget the meeting with 7 of us crammed in our very tiny conference room in Nariman Point looking at a demo video where Harsh was at a Diesel store mixing and matching looks on a touch screen powered by (then) addSale. The pitch was that retail was going to go digital and in order to stay relevant, physical retailers and brands needed to up their game and introduce digital experiences in-store to enhance sales. While in February 2013, this required a little bit of mind-bending by us. Harsh, Farooq and SMG exuded confidence, conviction, optimism and a real passion for solving for this Physical-Digital divide. That is what we bought into. Their conviction and commitment.

Over the last 6 years, spending time with the founders and the team has been like being in an entrepreneurship boot camp of sorts for me. I have learnt that doing more with less is an art, but building a data-driven organisation is a science. For a founder, knowing and believing in their purpose is central to persevering and ignoring the noise that surrounds them. Brutal honesty and transparency is directly linked to speed of execution.

To paraphrase what Farooq says, “great leaders build great cultures that build great companies”, (read the full blog here for more on Fynd’s culture.) and there are two things that have really stood out for me.

Data-driven has never been a buzzword, it is a religion at Fynd. Every (and I mean every) single person in the company is an expert on all the internal data systems and SQL literate. This means, that everyone can query data and find their own insights that help them take better decisions in real-time. There are giant screens all over the office that are constantly streaming dashboards. Transparency rules here.

The second is their grit. Farooq says “ We have had a fairly difficult fundraising history, but that has never stopped us from thinking big and then executing relentlessly.” It is this ability to never give in to what looks impossible, but to in fact turn that into an advantage that has made the Fynd team and their journey special. It is their infallible grit and grind that keeps them moving forward.

Kae Capital was the first institutional investor in addSale which rebranded to ShopSense and then again in Fynd. We have been privileged to see this journey from its inception to rapid scale to exiting an investor who has big plans for retail in India. We wish the Fynd team the very best on this new adventure of theirs.

We have always backed exceptional founders through good times but especially through bad times and will continue to do that.