Multi-chain, Cross-chain Interoperability and Composability Explained

Interoperability implies the seamless transfer of assets (fungible or non-fungible) and messages, while composability essentially implies shared infrastructure/effective cloning of dApps.

The Web3 ecosystem has taken off over the last two years. What started off as a whitepaper by the pseudonymous Satoshi Nakamoto back in 2008 has evolved from the first L1 – BTC (a prototype of sorts), to the arrival of the now dominant ETH (Ethereum), which drew the imagination of developers from across the globe with its smart contract functionality.

Now with other L1s like Solana and Avalanche, L2s like Arbitrum and Optimism, and even multi-chain ecosystems like Polkadot, the Web3 space has become massive.

The top 15 blockchains store  $10 billion  in value each, with ETH and BTC together contributing almost $2 trillion.

But these ecosystems are growing in silos –

Ethereum, the largest ecosystem, has the best developer pools. Most programmers are comfortable with ETH UX/UI, languages, and smart contracts but with the current PoW (Proof of Work: requires miners to solve a cryptographic equation by trial and error) mechanism, the chain is suffering from poor scalability due to gas fees.

This is despite having the best security. It is said that ETH 2 with PoS (Proof of Stake: requires miners to stake all or a portion of their coins in order to validate transactions) will be much faster and cheaper.

Solana, which is currently the most prominent Proof of History based (sequence of computations that can provide a way to cryptographically verify the passage of time between two events), non-sharded chain, has high transactions per second (TPS). However, developers are still getting used to Rust, and with the core use cases being built around gaming, it’s becoming another siloed ecosystem

Terra, which aims to become “DeFi Central”, and seems to be doubling down on DeFi use cases with its array of stablecoins and innovative DeFi protocols, is also becoming another fascinating silo.
blockchain

What encompasses interoperability and composability

Interoperability implies the seamless transfer of assets (fungible or non-fungible) and messages, while composability essentially implies shared infrastructure/effective cloning of dApps, meaning one should be able to deploy any dApp on any chain with minimum friction and time.

Each ecosystem has its core strength, core use cases, core set of developer pools and liquidity pools. Just like economies benefit from trade – blockchains benefit from trading functionality, assets, liquidity pools, etc.

The vision is to enable developers to deploy dApps from any chain, onto any other chain in an almost no code format at scale.

This entails the seamless sharing of ecosystem strengths through smart contract calls or even on tools abstracted one layer above the smart contracts themselves.

For example –

  • Computation (think logic and calculations, like those required in gaming) on SOL/AVAX smart contracts (depending on the kind of use cases)
  • Transactions (meaning buying or selling, but not settlement) happening on SOL
  • Finally, settlement occurring on ETH (eg. when someone pays using VISA or Mastercard – that is not a settlement. Settlement comes weeks after that.)

However, interoperability and composability today are broken. The future is not cross-chain vs multi-chain, but cross-chain AND multi-chain, we will need both –

The mode of connecting ecosystems today is cross-chain bridges. This is where we enter murky waters – i.e. the cross-chain vs multi-chain debate, which is at the heart of it all.

With bridge security mechanisms becoming a core piece of debate (bridge hacks leading to stolen tokens – like the Wormhole hack), a large chunk of the population believes cross-chain is not the future. Ethereum founder Vitalik has explained (here) why it is always possible to override consensus on bridges, making them a losing proposition.

This leads us to multichain ecosystems, with the core idea being shared security. For example,  the Polkadot ecosystem is an “internet of blockchains” with shared security, shared virtual machines (think computations, logic) with the concept of creating new chains called parachains.

So not only can the chains communicate with each other seamlessly and transfer assets, the security risk is much lower.

However, even with two  “Internet of Blockchain” ecosystems coming up with their individual shared securities,  they will still need to communicate with each other! Hence, bridges cannot be taken out of the picture altogether unless there is a completely new mechanism to substitute them.

Overall, we want to make bets on infrastructure plays, which will enable a multichain interoperable, composable future. This can include Tooling/Infra or Ether plays on Polkadot (think governance, no code plays, etc.).

This also brings in Protocol based interoperability standards (think cross-chain smart contract enablers, messaging layers, function call layers, interoperability standards, etc.), also containing DAO tooling which allows for multi-chain functioning, etc.
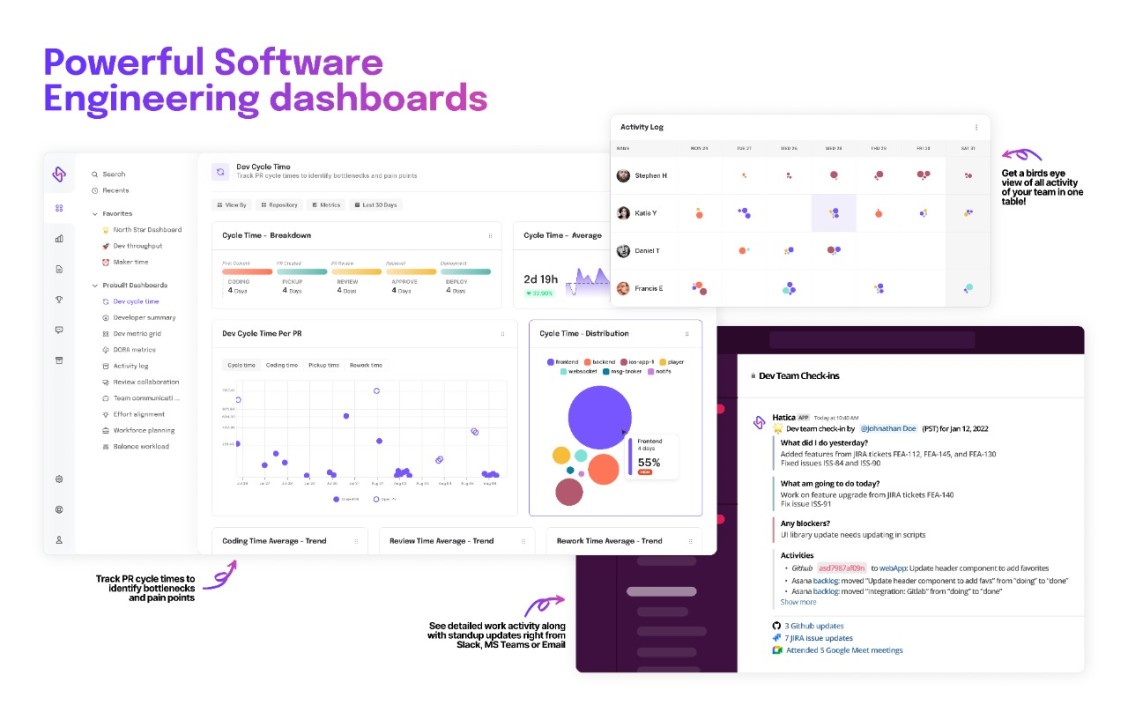
Investment in Hatica: Engineering Analytics to Boost Developer Productivity

The demand for software developers is ever-increasing! Digitisation, cloud adoption and software stack globally are driving this demand, amongst other things, but there is not enough supply. According to the State of the Developer Nation report, in 2021 there were 26.8Mn active software developers in the world and they predict it to reach 45Mn by 2030. This makes it a very large and growing market.

Software developers use multiple tools for their daily work and a lot of precious development time is lost in low-value work of context switching between tools, collaboration, documentation, version control, duct taping the issues etc. There is a developer experience gap. Strong dev tools can bridge this developer experience gap and improve a developer’s experience across the entire workflow.

Dev tools are an array of products focused on developers to help them build, deploy and collaborate on a daily basis. Some of the global leaders in this market are Github, Slack, JIRA, Browserstack, Snowflake, Postman and Datadog. Dev tools have seen massive growth in the last few years. There are more than 73Mn developers on Github, with 16Mn+ developers added in 2021 alone. Snowflake reported stronger than expected Q4 2021, with revenue rising by ~117% to $107Mn. A shift has been witnessed, from a ‘Build and Buy’ decision-making mentality to a ‘Buy and Build’ approach. Developers are now open to buying platforms which can help them decrease the time of development.

This shift is further fueled by remote working. The Dev tools market has experienced tailwinds from this increased digital adoption. The pandemic forced teams to shift remotely, which has further aggravated the problem of collaboration and communication. Many SaaS tools are building for the future of work to make this transition easier, without affecting the productivity of teams. Developers are one of the most expensive resources of a tech startup, and any reduction in productivity is a big loss in terms of money and timeline of projects. According to U.S. News, the median annual salary for a software developer is $101,790, which will bring the cost of the average developer minute to ~$0.81. Therefore, every wasted minute of developers potentially impacts the company’s cost structure and profitability. Companies are now becoming more receptive to dev tools to ensure that most of the developers’ time is spent on actual development.

High-performing engineering teams are essential for the success of companies as they can release products to market faster. There is a need for tools which can empower them to manage their daily tasks- context switching, collaboration, etc. in an efficient way. Developer productivity tools is a massive emerging market to solve this problem.

We are happy to back Hatica, as it aligns well with our thesis on developer productivity and the future of work. Hatica has been cofounded by a couple of experienced techies, building a global SaaS tool to provide an engineering analytics platform to boost developer productivity. Embedding the culture of remote work internally, they have built a powerful product to improve engineering efficiency and optimize dev workflows. Hatica has early customers from US, Europe and India. We are thrilled to be part of this journey and believe it has the potential to become one of the top engineering analytics platforms globally.

Alt Protein: The Next Big Thing

The post-COVID era has changed the way people think of health, nutrition and the environment. With this, a small but promising community of startups have begun India’s chapter of the Alt Protein landscape in the last few years. Over 3Bn USD has been poured into the Alt Protein category in 2020, around the globe. In India, we are at a nascent stage, perhaps right before it reaches the inflexion point. 

How large is the market?

In India, this nascent but promising market of plant-based meat is estimated to be around 200-500Mn USD by 2022 (GFI). The plant-based dairy industry is expected to reach 68Mn USD by 2024 (GFI). However, if adoption ramps up, it has the potential to reach $4Bn in the next 5-7 years. Adoption rates will become clear once commercial production starts for many of the players in the Indian market, who are currently market-testing their products or are in the R&D stage. An observable trend is an increase in the consumption of meat as a by-product of nations transitioning from developing to developed countries. Naturally, as disposable incomes increase, more people are likely to spend on meat consumption which is otherwise seen as a luxury. 

Why is plant-based food important for India?

Contrary to popular belief, we are not a vegetarian nation. Over 70% of consumers in India identify as non-vegetarians, but unlike the West, our frequency of consumption of meat-based products is relatively low. At present, Indian diets are predominantly cereal-based, and 60% of protein is derived from cereals that have poor digestibility and quality. 80% of India is protein deficient.

India is also facing a double burden of malnutrition and an increasing share of global Greenhouse gas (GHG) emissions (6.55%), making it the third-largest contributor to anthropogenic GHG emissions, a lot of which comes from the animal slaughter industry. Analyses of the environmental impact of plant-based meat showed that plant-based meat production uses 72-99% less water and 47-99% less land. Furthermore, it causes 51-91% less water pollution and emits 30-90% less greenhouse gas emissions. 

Process of developing Plant Based food

Recognising that any plant-based food company is a food science tech player first, and then a consumer brand is important. Being a brand is a long-term possibility but should not be the focus in the initial days when consumer adoption is unclear. There is a technical process involved in developing plant-based protein, and getting it to its final form.

Why is Plant-based food expensive?

Protein isolates are available to all players in the market. The basic material, in this case, protein isolate, is available at cheap prices to all, but it’s the additional flavouring, additives and preservatives which go into the final product that makes plant-based food expensive. These additional products are called ingredients and having control over the ingredient formulation is a strong way to have price parity in the long run. For a few players, high prices are also due to the cost of extrusion machines in the supply chain.

The price per kg comparison of the majority of the products across plant-based meat, dairy, and seafood are nearly 2-3x more expensive than their conventional counterparts. There is a significant scope for this to come down in the next 5 years as infrastructure improves.

Challenges and opportunities in this market

Lack of awareness: While Indians are massive consumers of raw plant products like lentils and pulses, processed product awareness and acceptance is prominent among urban consumers only. It is slowly picking up in smaller cities with the support of government campaigns.

Infrastructure challenges: India’s cold chain storage and transportation capacity is still ill-equipped to handle its fresh produce volumes, despite recent government efforts, making intra-state transportation challenging and costly.

Constrained R&D Ecosystem: India’s overall R&D spending as a percentage of GDP is lowest even among BRICS nations. Government institutions are restrained by funding challenges.

Low meat eating: Even people who eat meat in India are primarily vegetarians, who consume meat once or twice a week, whereas in the West, meat eaters consume meat three times a day.

Price elasticity is very high: When it comes to chicken consumption, the prices of Plant-based meat are 2-3x compared to the incumbents

Availability of Talent: Another more fundamental issue with this space is the lack of quality senior-level talent in the industry. The IT sector boom was facilitated by a lot of Indian overseas talent returning, if this happens for this sector as well, we could see faster growth. 

Despite its challenges, the market continues to grow and provides a lucrative opportunity for many players to build for this. In the next 6-12 months, a lot more activity especially on the commercialisation of these products will take place, adding another layer of insights about this space. 

Kae Capital is looking forward to connecting with more startups that are building for this category. 


Rise of New Creator Economy, Powered by Blockchain

India is one of the youngest countries globally and has the second most internet users after China. Post COVID-19, the average time spent on the internet has increased significantly and a large proportion of this time is being spent on social media. The quantum of content created and consumed has grown manifold over the last five years – signalling the advent of a massive creator economy.

The creator economy is built on the back of creators/ influencers monetizing their online content. Online creators are emerging in multiple categories: artists, fashion bloggers, musicians, writers, live game streamers, stock market traders, educators, and business bloggers. There are more than 50Mn creators globally spread across platforms like YouTube and Instagram. There are ~ 10 Mn Instagram accounts in India with over 10k followers and we estimate that approximately ~5 Mn are active/semi-active creators.

This number is rapidly growing year on year with a large number of young Indians entering the fray incentivized by aspirations to be recognised for their passions/hobbies while also getting an opportunity to generate parallel income or in some cases primary income streams. This is a particularly interesting phenomenon given that the revenue streams are still fairly restricted in the Web 2.0 paradigm.

The creator-consumer relationship is one which involves creators sharing content on YT, Instagram which the users can view (images, GIFs), watch (clips, movies) or hear audio where monetization is often restricted to ad-based revenue, or brand contracts where the payment from brands is unpredictable, the terms are often black boxed. Additionally, there is no guarantee on subsequent contracts. The creator economy, both in India and abroad is highly skewed from an earnings perspective – for example in the US – 80% of the earnings come from 20% of the creators.

Within the Indian market – creators earn primarily from Youtube and brand partnerships. Globally, there are 3-4 more sources of earning like Patreon, Onlyfans, etc. But their participation is largely restricted to Western economies. Our internal market sizing (for India) would skew the Indian creator economy significantly towards the top segment of the creators as well.

The creator economy in India is currently constrained by skew, lower ticket sizes and disproportionate bullet payments and manual/unscalable operations. In order to enable creators to drive engagement and retention, some founders have built vertically focused platforms so that UIs and workflows are tailored to specific categories, for eg. Discord started its platform with gaming.

Despite this, the existing platforms are very centralized. In Web 2.0, central social media platforms like YouTube and Instagram decide how much a creator can make based on the views. These platforms own your content and decide the monetization terms and as a result, a major chunk of money is flowing to the top creators and the platform itself.

With existing revenue streams putting a cap on the TAM, we believe Web 3.0 will solve both the earning capacity of creators while also driving higher engagement with the fans – significantly driving up the market size in the coming few years.

Through blockchain and Web 3.0, the earning power goes back into the hands of the creator. Web 3.0 inherently decentralizes value. It is disintermediating these central platforms, allowing creators to have ownership of their work and allowing them to decide the best value for their art. A critical piece of this decentralization is NFTs or non-fungible tokens.

NFT capabilities allow creators to earn in perpetuity through every transaction of their creation. Tools have emerged to convert different content formats into NFTs. Globally, creators are making thousands/ millions of dollars in NFTs. CryptoPunks is one of the earliest NFTs launched and has more than $2.2Bn in total trading volume (https://dappradar.com/nft). Few weeks ago a CryptoPunks NFT was sold for over $500Mn.

NFT marketplaces have received tremendous traction. OpenSea, which is the largest NFT marketplace, has passed a total trading volume of $10Bn in Oct’21. Rally is another platform where creators and communities build their own social tokens. NBA TopShot, where you can own top NBA moments, has facilitated more than $737Mn of total trading volume (https://dappradar.com/nft)

Axie Infinity is an NFT-based game that has grown exponentially and has made more than $3 Bn in total sales since its launch in Mar’18. Its play-to-earn model has created a new category of games. On Axie Infinity, players acquire unique digital pets (Axies) and battle to win in-game currency, which can be traded on exchanges. Even Indian celebrities like Amitabh Bachchan and Salman Khan are also jumping on the NFT bandwagon making it popular in India.

BitClout has enabled creators to form a platform to enable content consumers to share opinions, with each opinion generating a fraction of the Bitcoins which are provided as income to the creators. Creators now have the option of creating their own storefronts – reward point mechanisms and workflows have been developed to incentivize creators and fans alike.

Companies across the globe are planning to build on Web 3.0. Facebook’s (now Meta) decision to move to Metaverse increases confidence in Web 3.0 and encourages more people/ companies to move to Web 3.0. Web 3.0 is redefining the digital world. The creator economy as a whole has a lot to gain from the arrival of the Web 3.0 paradigm.

Rally of New Traders!

The NSE has 19Mn active clients of all stockbrokers combined as on June 30, 2021, an increase from 12Mn on June 30, 2020, a jump of 58% in one year. Zerodha is the largest, accounting for 19% of clients (up from 15% last year), followed by ICICI Securities and Upstox. (Zerodha has ~2Mn Active clients, ~1Mn Inactive clients)

The number of investor accounts with Central Depository Services (India) Limited (CDSL) has more than doubled from 21.2Mn in March 2020 to 46.4Mn in September 2021. In fact, more than half of the additional 25.2Mn accounts — 13Mn — have come in the last six months between April and September 2021. Even NSDL added nearly 27 lakh accounts between April and September 2021.

Okay, but how many of them were retail investors?

In the last year, the number of retail investors has jumped more than 41 percent, data available with BSE showed. More than 70Mn investors were registered with BSE as of July 8.

Retail investor participation continued to grow exponentially in FY21 as well, with almost 4.5 million retail investor accounts being added in just the first two months of the fiscal year. The total number of retail investors increased by an astonishing 14.2 million in FY21, with 12.25 million new accounts being opened on CDSL 1.9 million in NSDL.

The result is that the Indian stock market is now dominated by retail investors. The NSE alone saw retail investors share grow from 33% in 2016 to 45% in 2021

Why will this number grow?

The industry has the potential to cross INR 100 trillion in AUM in the twenties. Reaching the INR 100 trillion vision during the mid-twenties can help the industry become the 11-13th largest asset management industry in the world from its current standing of 17th largest asset management industry. BCG estimates indicate that achieving this growth will require a 5x increase in the investor base from 20Mn in 2020 to 100Mn investors soon.

The problem is that the new investors coming into the market do not fully understand the market. A large number of them are in their 20s and 30s taking massive positions in F&O which is a much riskier asset class. A study by ISB showed that the majority of them tend to exit winning trades quickly and hold on to losing trades longer (A textbook mistake done by rookie traders who half gamble due to lack of understanding of the markets)

This is a gap that the market has not been able to fill so far. New traders are not as savvy as the older ones. While there may be enough YouTube videos or upskilling players helping them pick up the tricks of the trade through theory and a few live trade sessions here and there, the vast majority of them do not follow the basic hygiene of being a trader, i.e Building a solid trade setup.

Now the question is – Are the existing stock brokers available in the market well equipped to provide this service to new traders? 

The answer would be No. New traders need risk management systems, a chart to track their daily earnings or losses, discipline in setting targets, stopping losses, and risk-to-reward ratios, which today is typically done outside of the brokerage platform and on excel sheets.

India, being one of the fastest growing markets for retail investors in the world with a large market still untapped, needs platforms that help regulate and bridge the learning curve for new investors/traders.

After all, investing in financial freedom is the winning bet of them all!

(If you are a company building in this space, do write to us at sarthak@kae-capital.com)

Creator Economy: Music Licensing Marketplace

The creator economy is buzzing now more than ever with YouTubers, Tiktokers, Educators, and entertainers having more influence than one could have ever imagined.

Everyone has been talking about helping creators monetize lately. And there is one such, rather less explored avenue for creators – in this case, Musicians, to make money for their hustle – Music Licensing.

What are we talking about?

Whatever music you hear in Public i.e inside restaurants, pubs, clubs, cafes, or live performances, everything is being paid for by someone licensing it. Someone created it, someone has to pay to use it. Makes sense right? Let’s even call it Music as a Service.

This must seem like a bizarre concept for most people in India, who think it is legal to casually play certain soundtracks at weddings, gatherings, parties etc. without paying for it!

Let’s get some statistics and a back story out of the way first before we deal with what Music Licensing is and if this can work in India.

The revenue from the recorded music industry in India is <INR1500 cr. and for the film industry is ~INR19K cr. Despite the direct relationship between the film industry and the music industry, the difference is stark. (Source: Deloitte | IMI report, IMI)

Why?

Archaic laws 

It’s estimated that around 2016 cr. to 2791 cr. annually is lost by the recorded music industry due to obsolete laws. And of course, piracy is an issue. They lose about ₹1,000 crore a year due to piracy, which, makes up for 67% of the market — (for context) the global piracy average is 27% (Source: 2019 International Federation of the Phonographic Industry (IFPI) – Indian Music Industry (IMI) Digital Music Study)

All right, so we are losing money in the recorded music industry, which means Musicians especially independent creators must be struggling as well!

Cue IPRS. The IPRS was formed in 1969. It is a non-profit making organization that issues the license for the usage of music and literary work.

So why exactly is the IPRS important?

Because this is a central body in India that collects all royalties from artists for their musical work. There are two types of royalties – musical lyrics a.k.a underlying works royalty and then there is the royalty from the recorded music a.k.a masters. The masters are what labels like T-series own and the IPRS collects the underlying works royalty.

Now, this is where it gets interesting. This allows for a marketplace to be built that allows creators a channel to monetize their music and recover all this lost revenue!

Most upcoming independent music artists are making music from their studios, bedrooms or studios in bedrooms!

For each track made – there is someone who would be willing to pay for it if it serves their purpose. One side would-be creators of music and the other side would be buyers of soundtracks (Agencies, media houses, a YouTuber making an unboxing video, etc.)

That’s what a music licensing marketplace is. Epidemic Sound is the global leader in this at US$1.4Bn valuation after closing a US$450Mn round in March this year. (Read here)

But, there is an issue with this in India. To explore that, let’s look at how music creators today monetize. There are 3 things to note here – Medium. Scale. Payouts

Medium

Most creators make or attempt to make money today via YouTube, Facebook, TikTok, Instagram or Twitch. In India, homegrown startups like MX Takatak and ShareChat have a corpus of ~13.5Mn each for creator payouts. (Source)

Scale

Globally, SignalFire splits creators into amateurs (46.7 million) and professionals (2 million +). Closer home, in India, there are about 100Mn creators in all. The active content creators would be about 10% of this lot ~ 10Mn.

Payouts

This is where the challenge comes.

YouTube is the largest platform for creators in India today in terms of payouts (revenue from ads, subscribers, likes, comments etc).

So for the sake of simplicity, let’s explore creators using mainly YouTube as the primary source of revenue – via ads. In this model, YouTube charges 55% while giving back 45% of the ad revenue to creators.

The irony is that most of the world is trying to skip ads or paying a premium to get an ad-free experience.

So a creator needs a lot of views before they earn anything substantial.

The end result is that 97.5% of YouTubers don’t make enough money (to even reach the U.S. poverty line, $12,140) Therefore, YouTube creators need to find other ways to supplement their advertising income.

YouTube India’s payouts to creators are easily less than $500Mn per year, which translates to $50 a year per creator (For easy calculation, assuming that most of the revenue gets evenly distributed among 10Mn active creators)

In fact, the topmost Indian YouTuber earn 70% less than their US counterparts.

So with such minimal earnings, the primary pain point to solve for the creator economy is to provide channels to earn revenue that consumers are today willing to pay for. 

A few companies have come and tried to do so but quickly pivoted models when they realized that there is an intent to monetize from the creators’ side, but a fairly low willingness to pay from the consumers’ side for most content – except for content on edtech, onlyfans or gaming platforms.

Music licensing marketplaces could have been an interesting channel in India but it seems like until the earnings per year per creator increases, this model will not scale beyond a point. Influencer marketing is another interesting space for this.

While globally, companies like Epidemic Sounds have become billion-dollar businesses through this, closer home, it may still be early.

Hopefully, with payouts rising and/or more channels of monetization emerging, it is likely that this ratio will correct itself in the next few decades.

The opinions expressed here are those of the author. They do not purport to reflect the opinions or views of the Fund or its members.

Hitting the Right Metrics is the Bedrock of Building a Sustainable Startup: Summarizing the Playbook

  • Solve for the right market
  • Find your customer
  • Hit product and channel market fit
  • Hit monthly and quarterly growth milestones

Strong metrics underlie the whole journey.

Strong leading metrics are a must-have, and startups are setting themselves up for failure if they don’t hit those benchmarks

Revenue numbers lag strong leading indicators. If there is a PMF, leading indicators will inflect first and become critical to track (not more than 3) to gauge product love.

Our goal through this post is to set good benchmarks for consumer startups based on learnings from our portfolio.

Genesis of metrics – and identifying healthy startup growth

The success of young consumer startups hinges on LifeTime Value (LTV) and acquisition costs.

LTV is the total value derived from a customer through their engagement with your product/solution. Growth is driven by new revenue (acquiring new customers and making them spend) and repeat revenue (repeat purchases made by previously acquired customers). High LTVs are driven by healthy repeat behaviour. Hubspot forms a great case study of how they  used LTV (with CAC) to diagnose unprofitable growth and double down on better channels (1)

Is there a case for high ticket size, low-frequency markets? There is, if such markets (wedding services, home design marketplaces etc.) drive enough value from that single transaction that justifies the customer acquisition costs. Further, they are more outliers than the norm. Most businesses need to drive repeat behavior to become sustainable.

With the overall theme being set, let us dive straight into some of the relevant models –

Consumer Tech

Most consumer tech plays are apps that involve people performing some action on the app – browsing, playing, placing orders, messaging, etc. which translates into having them spend time on the app.

High engagement/time spent leads to better monetization through in-app purchases, payment renewals, etc. which leads to higher LTVs – you don’t have to keep acquiring new users to fuel growth.

DAU/MAU* OR WAU(Weekly)/MAU become critical metrics to gauge product performance – and it is generally one of the most preferred measures to understand how well the product is solving for the demand.

DAU/MAU gives the % of monthly users who use the app daily. (Similarly for WAU/DAU)

Are your users finding a need to open the app frequently? Think of the number of times you open WhatsApp or Chrome in a day. This makes it critical to monitor DAU/MAU (or WAU/MAU) religiously.

On average, DAU/MAU should range between 10-20% depending on the natural frequency of use as per Sequoia’s ‘14 benchmarks, with truly engaging apps posting a 20%+ DAU/MAU.

The benchmarks below are global, and we use them depending on the category.

Twitter – 30%

Facebook – 50%

WhatsApp – 70%

Gaming apps would typically trend over 30-40%.

Over the last few years, more social/community-driven apps have entered the market and enjoy higher engagement values.

Referring to a16z’s social app benchmarks – the social consumer tech categories like social shopping, discovery platforms and communities on an average rank between 30-50%, read here (2)

D2C/Internet first Brands:

Internet brands tap into fast-growing high-frequency categories through online discovery and purchase.

Transaction Models

We want to tap categories with high LTVs – built through strong repeats. Repeats are the best indications of PMF for brands – measured as the % of monthly customers who buy again. The timeline of the repeat purchase depends on the category, but we feel the following benchmarks will be healthy bets to indicate strong product love.

Our experience from our D2C portfolio indicates that good repeats range anywhere between 40-60% with all of our most successful brands tracking in those ranges and some shooting over 70% too.

Categories falling into high-frequency consumption – ideal repeat % should be between 50-60% – these include products like skin care, hair care, sanitary pads, cosmetics, casual clothing, etc.

If we are looking at lower frequency purchases like ethnic Indian clothing, we should aim for 40%-50%.

Subscription Models

Subscription brands also track retention, measured for a cohort.

Brands who have hit PMF would track at 3-month retention upwards of 50-60%.

We have seen 90-day retention exceeding 80% within our Portfolio, exceeding the global gold standard of consumer subscription businesses, Dollar Shave Club, which claims to have a 60% 3-month retention. (3)

Conclusion

LTV is at the heart of profitable growth –

  • For D2C brands, high LTVs are a result of strong repeats and a healthy repeat % will be between 40-60%
  • For consumer subscriptions – strong LTVs are driven by strong retention -50-60% 90-day retention indicates strong retention
  • For DAU/MAU – strong app engagement measured by DAU (or WAU)/MAU drive good LTVs and in our opinion, strong consumer apps should try and exceed 25%

Usage/Engagement and Repeats drive sustainable venture growth and will continue to do so in any variation of the digital economy.

If you feel you are hitting such numbers – please write in at – sunitha@kae-capital.com and sarthak@kae-capital.com . We would love to hear from you!


Future of Work

Historically, every few decades, work got disrupted by major events like the industrial revolution in the 1800s, WWII in the 1940s, the adoption of PCs and the internet in the 1990s, and the pandemic in 2020. The pandemic forced us to reimagine the way we used to work. Last year, it took us by surprise, forcing cities into complete/ partial lockdown to contain the virus. It made the global workforce stand still and forced organizations to rethink the way we work. It forced employers to make changes to enable work without the need to physically come to offices. This led to the adoption of remote work globally. Companies were forced to rethink how they operate, managers had to find ways to manage distributed teams without compromising on productivity and employees had to find tools to collaborate with colleagues/ clients while working remotely.

The pandemic fundamentally questioned the nature of work. Bringing all employers whether MNCs, tech startups, or homegrown businesses to adopt remote work. In some ways, remote work has made our lives much easier. It has removed the hours of commute and the frustration of being stuck in traffic. No need to wake up early, get ready in a suit and leave hours before the office timings to avoid traffic. It gave us the flexibility to work from the comfort of our homes in our jammies or from the Himalayas or from the beach. People got the opportunity to stay with their parents for months. Internet consumption has increased as more people are stuck at home, looking at their mobiles for learning/ entertainment. The gig economy has thrived as people have realized they can earn decent money without a regular 9 to 5 job. The creator economy has grown exponentially in the lockdown, we have seen more creator focussed startups than ever. On the flip side, working from home for months has dissolved the boundary between work and home. People are working more than ever with no real break time with their colleagues/ friends to relax. Employees feel more disconnected, lonely, and dissatisfied leading to anxiety and depression.

From the past couple of months, things are getting back to normal with increased vaccination and a decline in active COVID cases. Cities have started to open up. Even if some employers are ready to get back to offices, employees are apprehensive. More than 3/4th of executives expect the typical core employee to be back in the office for 3 or more days a week, whereas ~3/4th of employees globally would like to work from home for 2 or more days a week, and more than 50% want at least 3 days of remote work, according to a McKinsey survey. This expectation gap might lead to a decline in job satisfaction and higher attrition. According to a McKinsey survey, 40% of workers globally are considering leaving their current employers by the end of the year.

Companies are contemplating whether to keep working remotely or get back to offices. Many companies across the globe are opting for hybrid, which is a mix of remote work and work from office, giving more flexibility to the employees. Google has announced 60% of their workforce will be working together from the office a few days a week, 20% working from home and 20% working in new office locations. Spotify announced the transition to a permanent flexible-work model with its Work From Anywhere policy. Twitter announced that employees can work from home forever if they wish. Uber earlier announced 3 days per week from the office but it received pushback from employees and had to change it to 50% of the time from the office.

People are choosing to leave their job rather than go to the offices. We are a knowledge-based economy and talent is the biggest asset of the organizations. Demand for good talent has skyrocketed recently as it is not only the Indian startups/ MNCs with which you are competing for the talent, you are also competing with the global companies. The workforce has truly become global, dissolving the boundaries of space and time. Tech hiring has become really challenging for early-stage startups. Developers are sitting with multiple offers in hand. Working from home provided the much-needed push for some people to start up or work on a side hustle. It can be seen by the explosion of users on no code low code tools like Bubble and Webflow. It has become very difficult to hire or retain good talent. To attract and retain good talent, you need to be at least as flexible/ hybrid as other companies.

Remote work has brought a global culture shift. Organizations need to make changes to bring more flexibility in the system on when, where, and how people work. The challenge is to decide how to be more flexible, and how to structure the hybrid workforce. There are some functions that can work in remote setup effectively like engineering/ design teams. Other business-focused functions like sales and strategy, where the degree of collaboration is more, might need to physically sync up more often. There are many questions that need to be addressed before going hybrid: How many days of remote/ WFH in a week? Which functions can go completely remote and which functions require some work from office? Deciding on full-time vs contract-based employees. How to ensure collaboration with some employees working from home and others from the offices? How to ensure productivity and innovation along with keeping the safety of employees in mind? Which tools to use to enable inter and intra-team collaboration, engagement, and team culture?

Now, the question is not “whether to go hybrid or not”. The future of work is hybrid. The question now is “how to go hybrid?”

There is no set framework for hybrid. Employers are experimenting to find a balance between their needs and employees’ expectations. Policies, processes, technology, and collaboration softwares need to be in place to make work more flexible. Tech focussed on the future of work is very broad, anything that makes working and collaborating easier whether you are working from physical offices, fully remote, or working in a hybrid setup. We will cover more on different tech platforms building for the future of work in the next article. If you are building software for the future of work or want to have a discussion, please write to veenu@kae-capital.com.

Lessons from the Upskilling Market in India

We spent the last few months evaluating companies that could potentially make or break the backbone of our country – The Unskilled Youth of India.

When we approached this sector, the objective was to understand whether solving the “Skill Gap” was a scalable problem.

To take a step back – the market size was huge. 18Mn undergraduates in non-tech courses graduating in 2020 alone and 5-6Mn on the Tech side. Plus the section of working professionals looking to upskill themselves (at least 20Mn in white-collar jobs). With edtech products being sold and bought at 20K+ INR per course, the overall TAM was clearly north of a couple billion.

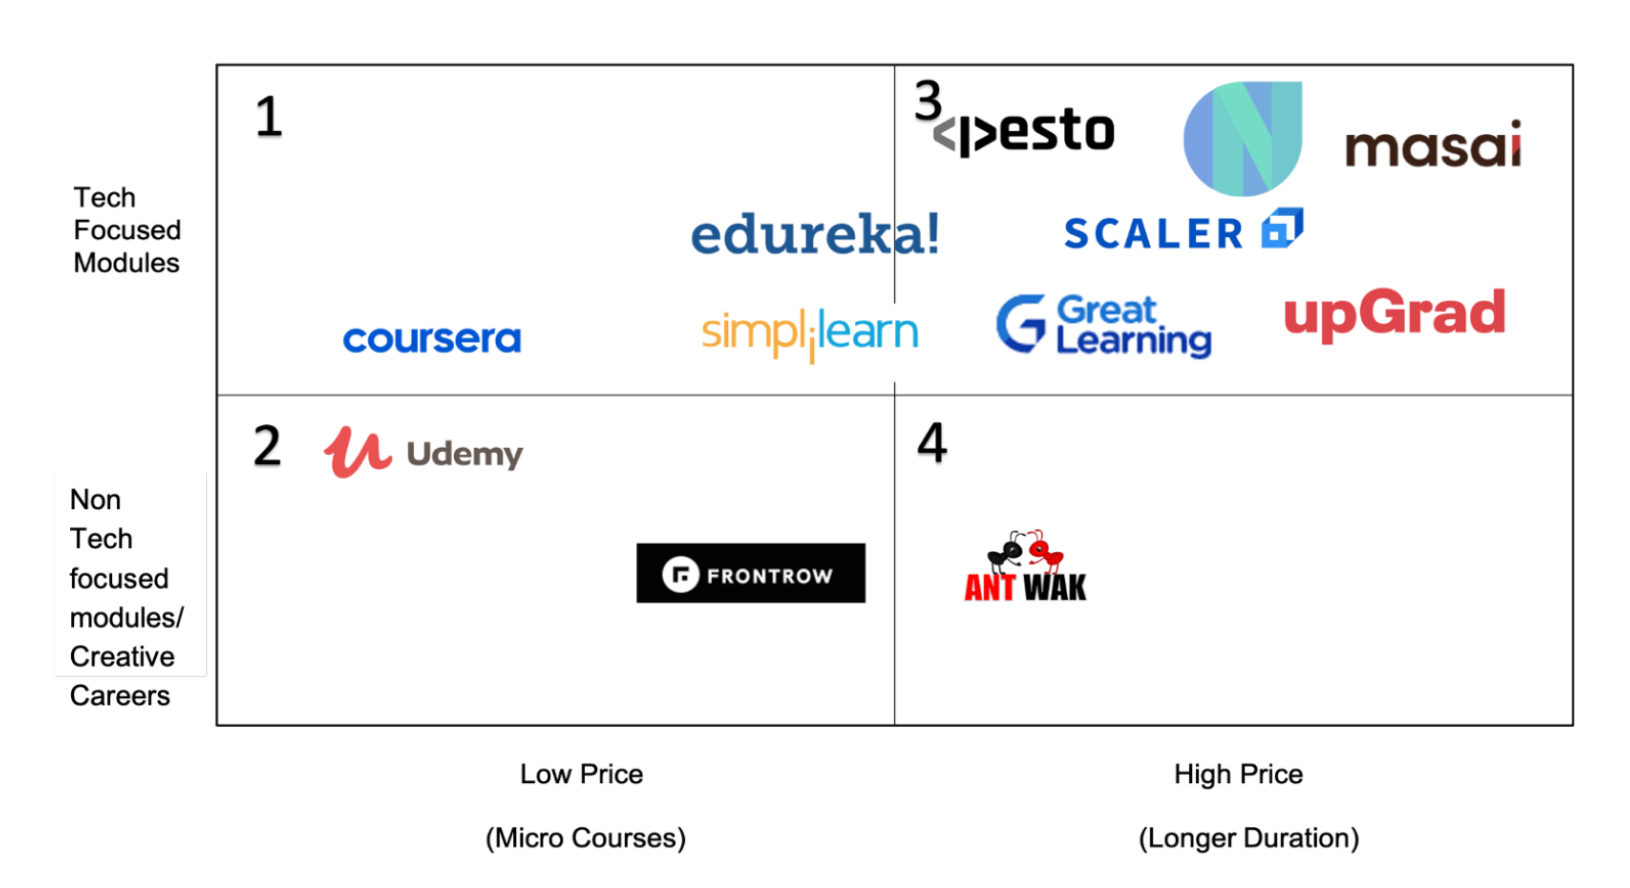
As we looked at this market, each player could be categorized on the basis of their courses, content type, and pricing (broadly).

With the rise in remote work and access to a highly-skilled tech workforce at 1/5th the cost when compared to the US, the market for tech-based upskilling & hiring was getting deeper and highly demanded in India. On a YoY basis, hiring in the tech sector grew 163% in June according to data from Naukri.com

But clearly, there seems to be white space for lower-priced tech-based courses and low or high-priced creative careers (or soft skills) focused on edtech players

 Now the question was

–       What differentiates the new players from the others in the market?

–       How do we solve for engagements & outcomes for the learners?

–       Can skilling reach the next half a billion at affordable prices?

The answers to these questions came from a few observations that we made from our discussions with founders building in this category, as below:

1. Companies focused on Upskilling had reached only the top 1-5% crowd of the country.

The majority of the courses were beyond the paying capacity of the majority of the people in the country. So how did the newer players make this more accessible?

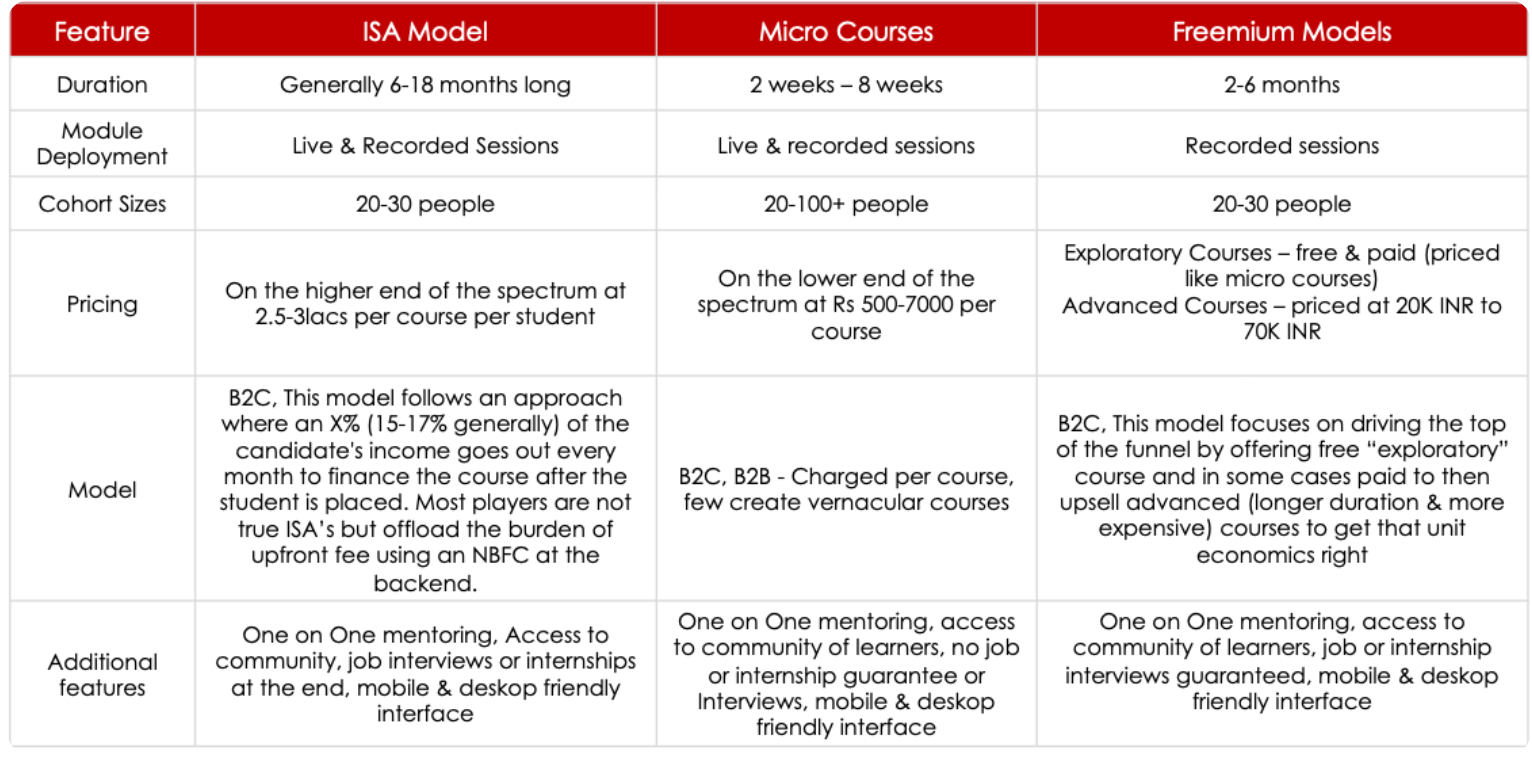
Most upskilling companies operate on either of the 3 models as shown below:


2. Why are more startups emerging in this category, when companies like Udemy and Coursera already provide micro as well as longer courses across both tech & non-tech domains? Where is the differentiation?

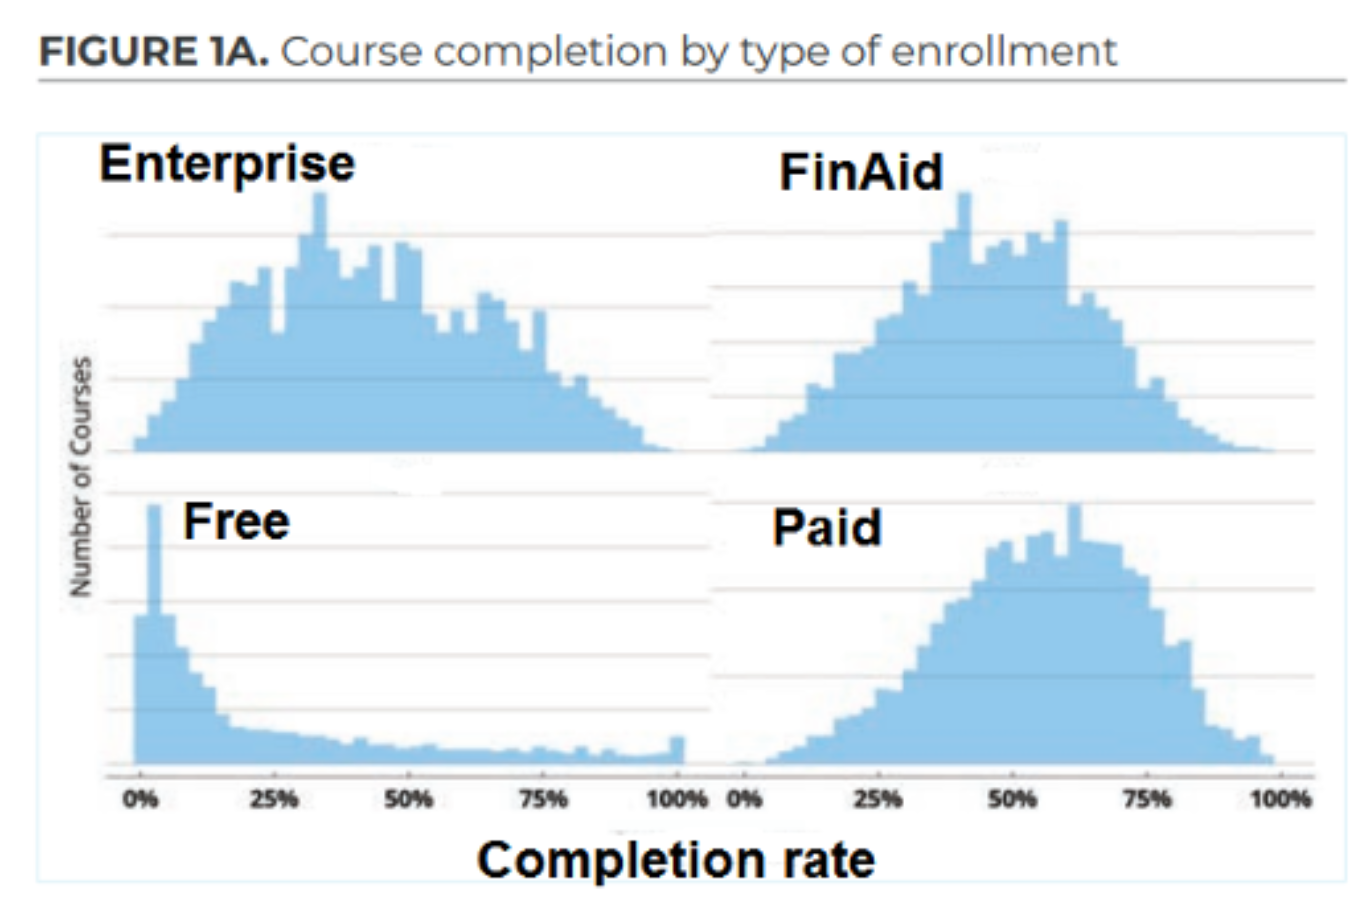
The differentiation came from a deep focus on outcomes & customer experience which Udemy & Coursera failed to address. For these companies, the course completion rates (% of people completing the entire course) were around 7- 10% until 2019. They did not focus on engaging the customer. They provided their courses like movies on Netflix. Nobody is going to binge-watch that!

But to their credit, Coursera published a report in 2020 which showed that post-pandemic, their completion rates for paid courses were averaging at ~55%. (Read Here)

Of course, being one of the largest players in this space at the moment, I would attribute the increase in this % to the tailwinds in the market for online learning and not to an improvement in the learning experience for the consumer.

People are looking for 2.0 methods of teaching online and clearly needed intermittent nudges to get them to stay engaged and complete the course. (If you have a different view, would love to chat at sonia@kae-capital.com!)

When newer players came to solve this, they identified that customers wanted to ask doubts, get real-time answers, connect with experts in the industry or peer learners and most importantly want to see an outcome more than a certificate. Most people will invest their time and energy if they either get a job, internship, or some real-world application.

3. This paved the way for a more holistic upskilling approach.

Companies focused on engaging the customer by improving the overall UI/UX, making the journey exciting with intermittent milestones, gamifying the experience using rewards and gifts, onboarding young industry experts (to increase approachability and relatability), focusing on partnering with companies that were hiring to directly engage with the learners with real-world projects and finally actually providing the network to get a job (no one actually guarantees a job, it is mostly a promise of getting access to 3-5 job interviews) at the end of the course

4. As competition increases in the seed stage for such companies, It is becoming harder to differentiate the newer players. Branding will become extremely important from Day 0

Beyond the courses themselves, all companies focus on similar offerings as highlighted in the table earlier, so selling the story of the brand, its teachers, its hiring partners and the unique power of its community will become critical nuances that a learner will scout for when selecting a course.

5. A major challenge with these models is that as the ecosystem matures, the cost of acquisitions is bound to increase.

As more edtech products get bombarded at people on a regular basis, it will be increasingly difficult to grab a piece of their mindshare. And thus, Customer Acquisition Costs will shoot up. Today it is anywhere between 1000 – 3000 INR for most companies in upskilling. Assuming this will go up by 20-25% each year based on a historical average.

At such CACs, Lower Priced Courses or Micro courses would have to either find extraordinary ways to acquires new users (B2C), or their LTV: CAC ratio would suffer in the long term.

In the short term, the relatively cheaper prices would make sense to acquire users fast, but for the company to scale to over a 100Mn in ARR at profitable unit economics would require them to eventually step up the prices, to ultimately land up in the same bucket as the ones following higher-priced/ISA models (anything above 20K INR per course at the current rates)

An interesting way some companies solved this is by onboarding celebrities as course tutors (following the masterclass model). By doing so, most of the top-of-the-funnel conversions came because of the traffic driven by the celebrity’s brand. This allowed them to continue at a lower price while keeping the paid CACs low. However, engagement for students may not be high here, which leads to low customer retention. Again, time will tell if this model breaks out.

6. Price of the course is hardly a differentiating factor for these companies in the long run. But a great hook to acquire new users.

The price of the courses is a culmination of the cost of creation of the course and revenue share for mentors/experts who helped curate the course among other costs. Courses that today are priced in the 1000 – 9000 INR category would eventually have to price it upwards as CACs increase.

However, offering good quality exploratory courses at cheaper prices or even free could create a strong funnel that could be leveraged to upsell the acquired user to buy more expensive courses to eventually justify the CAC.

7. Learners pay for the content, but is Content really a moat anymore?

Companies that have a high course price, generally invest in creating their own courses in partnerships with industry experts or leaders. Which is why they were priced so high.

Today, edtech ecosystem all over the world has matured enough that there is plenty of great good quality content available out there. Using the existing content on the internet, content can be created in a couple of hours with one or two engineers and with one line of code. Earlier, it took an entire content, R&D, and engineering teams several weeks & months to create courses to sell. To play the devil’s advocate, one can say that this content will not be original and hence of subpar quality in comparison.

Truth is, it probably may not matter that much. No student gets to go through the entire content before they pay for the course. If companies are able to drive top-of-the-funnel conversions by using free content and then effectively upselling them higher-priced modules, it could still help with keeping the CAC low. It seems very hard to believe that courses that are created in-house will be extraordinarily different from the ones using NLP over the next 10 years. But low-quality content could create poor word of mouth, a powerful tool that if played poorly could reflect in low NPS scores.

(NPS for a lot of upskilling companies is north of 60, which is extremely high in the category and to our understanding could become the new benchmark in edtech.)

The ecosystem for upskilling companies that are already in the market is ripe and it is a great time for the existing players to grow but it would get competitive as several newer players have come in the last couple of years. The market is large and is ever-increasing as learning is seen as a lifelong activity. For the players coming post-2020, it would get harder to differentiate and maintain healthy margins as acquisitions become expensive at scale. Edtechs will have to figure out innovative ways to get to mass India while being profitable.

 To sum this all up in one line – for any new player coming in the market, the key would be to crack Branding + Customer Experience + Customer Acquisition (Retention) + focus on outcomes before anything else, to be able to capture the market

The current school of players have plenty of scaling to do on their hands and we can hope that this would pave the way to edtech 3.0 soon

Embedded Ecosystems Built on Motherships Using API Networks/Gateways

Understanding History – Digitization Waves and How They Took Place

The Indian digitization story has been a unique one – the Jio rollout and low smartphone prices led to an unprecedented digital inflection point, which in turn led to rapid adoption in new technology paradigms like mobile first and on-demand (eg. Uber, Swiggy). Large consumer tech companies in Edtech like Byju’s, in E-commerce like Flipkart, heralded the first wave; the emergence of social commerce companies like Meesho and a new wave of SMB SaaS players like Khatabook, Dukaan heralded the second wave.

As a result, various technologies – which include new-age startups/platforms, legacy on-prem and cloud softwares have penetrated different markets creating distinct layers over the years.

If we look at the current landscape, very broadly – there would be three markets categorized by different levels of technology penetration –

  • New age consumer and business technology plays which have been created in the last 5-7 years – think Flipkart, Byju’s, Swiggy as consumer plays; Shopify as business plays
  • Legacy technology products being used primarily by businesses – think Tally, miscellaneous legacy AutoCAD technologies being used by architects
  • Semi-offline markets where smartphone and WhatsApp penetration is high – think Kirana stores and small retail businesses. These are semi-offline because they have reasonable WhatsApp and phone penetration and have recently seen Khatabook, Dukaan adoption.

Each market has seen the emergence of what we may think of as Motherships

Our objective is to identify these Motherships where embedded ecosystems can be built. The future of venture backable businesses will be embedded growth – built on the back of Motherships whose core functionality is limited to one or two use cases. The goal is to significantly expand their use cases and subsequently expand their TAM – by solving for the end-user through functionalities which are difficult to build and scale.

Creation of Embedded Ecosystems on Platforms Solving for Single/Limited Use Cases

We want to make platforms into Ecosystems which give users more reasons to use the platform and drive greater network effects. Potential motherships have 1 or a maximum of 2 use cases – for example, Tally’s main use case is data entry for accounts, Swiggy solves primarily for food delivery and restaurant discovery, or a Khatabook solves primarily for accounting/maintaining ledgers, but each of these platforms is used by a large chunk of the population.

To summarize – A few common traits of motherships

  • They are technologies (software/hardware) which have a reasonable presence/penetration in core industry categories
  • They have 1 or maybe 2 core use cases – and their bandwidth is restricted to these specific use cases
  • There is a potential for new functionality which is not their core competency

Motherships can be single platforms OR multiple distributed touchpoints:

  • Shopify – Single Platform
  • Credit Cards – Distributed across several users

Mapping out possible motherships (this list is not exhaustive, would love your thoughts on this, do write in – sarthak@kae@capital.com)

Building for the B2B2C/B2B2B Users, Where Platforms Face Significant Challenges in Developing New Capabilities/Functionalities

We will notice most platforms have a dominant position in their respective markets, so what is to stop them from developing the functionality in-house?

The counter to the above argument is to tap into those APIs/functionalities which need high bandwidth to develop and maintain. These will be easier to “outsource”/ “unbundle” – and solving for this seamlessly is needed to be done.

Additionally, new functionalities may add a structurally different revenue stream, significantly driving up TAM – Embedded marketplaces, Embedded NFT gateways are strong examples of such functionalities.

The possibility to charge per API call opens up potentially massive markets with highly scalable models.

The new functionalities can include (and are not limited to) –

  • Embedded product marketplaces for procurement – imagine excel sheets/Tally with an embedded marketplace, where building supply is a challenge
  • Embedded service marketplaces
  • NFT/Blockchain functionality which requires high processing power/costs
  • Deep learning which requires high processing power/time, very deep expertise
  • Cybersecurity
  • Reverse Fintech – Fintech players/Fin. Institutions being used to distribute other products/services

Embedded Marketplaces, Deep Learning, Blockchain – and then some more!

These are some of the plays which we are exploring, and we would love to hear from you if you are building something out in this space.

We are particularly interested in discovering –

  • Embedded Tools (for Eg. NFT API Tools, Cybersecurity API Tools, Deep Learning API Tools) being built on B2B Marketplaces

AND

  • Embedded B2B Marketplaces on commonly used SaaS/Software tools like Excel, Tally (including platforms like Khatabook maybe!)

Similarly, Embedded tools built on Consumer/Prosumer Platforms/Marketplaces are of interest as well.

If you feel you are working on something of this sort, or know someone – we would love to speak to you!

Do write to sarthak@kae-capital.com